Plan your move
Know what to ask, and who can answer.
Five resources help you understand monthly costs, learn how financing works, find your starting point, read the land under a community, and write a planning brief. Everything here is preparation. Credit and lending decisions stay with a licensed lender.
The approach
Useful long before any paperwork.
These resources help you arrive at a first conversation knowing what you want, what shapes the cost of owning a home, and who decides what along the way.
They do not evaluate you, and they cannot tell you what a lender will decide. That answer comes only from a licensed lender, working from your own documents and a specific property.
Five resources
Choose where to begin.
Each resource stands on its own. Together, they lead to a brief you can bring to a first conversation.
- 01Monthly cost componentsLearn the parts of a monthly housing cost, then build a list of questions for the people who price each one.Explore
- 02How financing worksFollow the steps from estimate to final approval, see who handles each one, and gather questions for a licensed lender.Explore
- 03Readiness snapshotAnswer five short questions and see what to read next and what to bring to a first conversation.Explore
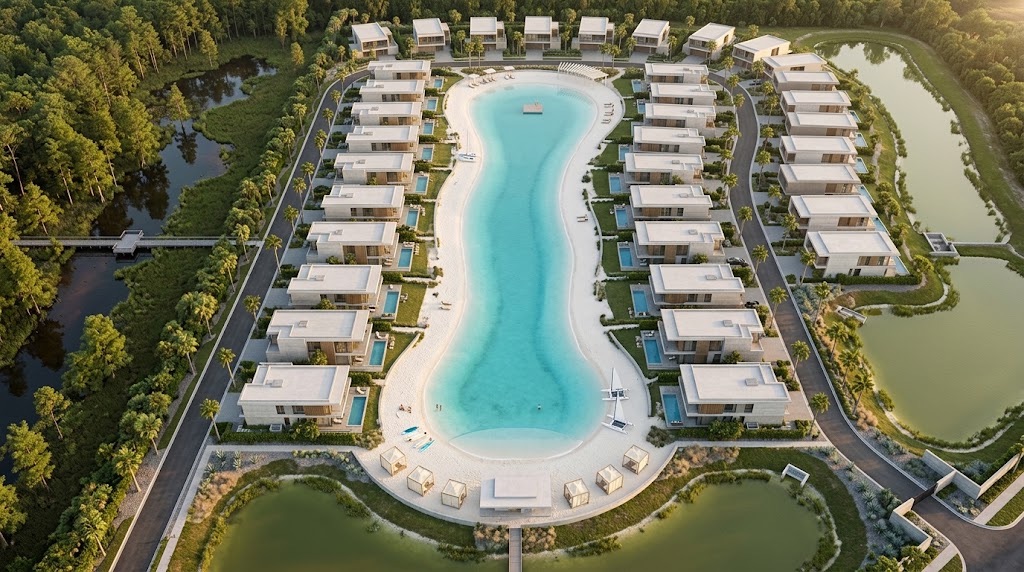
- 04Reading the landLearn why high ground decides where a lagoon belongs, and what to ask about any community’s land.Explore
- 05Planning briefTurn your direction, timing, and questions into a brief you can review and print. Nothing is sent or stored.Explore
Know the terms
Four terms that sound alike.
Much of the confusion in a home search comes from treating these four as one. They differ in who issues them, what is reviewed, and what, if anything, is committed. Lenders also use the names differently, so ask each lender what its version includes. Read the longer explanation.
- Payment estimate
- A planning figure built from assumptions about price, the amount borrowed, taxes, insurance, and dues. You can prepare one yourself, or a lender can prepare one with you. It is not the Loan Estimate, the formal disclosure a lender issues after an application.
- Lender prequalification
- An early read from a licensed lender, usually based on information you report and sometimes a credit check. It is not a commitment to lend. Only a licensed lender issues it.
- Lender preapproval
- A conditional statement from a licensed lender after it reviews credit and verifies documents. It usually carries conditions and an expiration. Only a licensed lender issues it.
- Final loan approval
- The decision on a specific loan for a specific property, made after full underwriting, which usually includes an appraisal and a title review. Only a licensed lender issues it, and only for that property.
Before you ask for an answer, know who has the authority to give it.
Clear limits
What this site does, and what it never does.
What this site does
- Explains, in plain language, what makes up a monthly housing cost
- Walks through the financing sequence and who decides each step
- Helps you build lists of questions for licensed professionals
- Provides a readiness snapshot and a planning brief that stay in your browser
- Suggests community and home pages that match your answers
What this site never does
- Collect credit, income, bank, or tax information
- Evaluate eligibility for any loan or program
- Quote rates, terms, or payments
- Recommend, rank, or refer you to a lender
- Take a loan application
Nothing you enter on this site is shared with a lender.
Important
General education for your own planning.
Everything in this section is general education. It is not financial, tax, or legal advice, a loan estimate, an application, a prequalification, a preapproval, or a commitment to lend. DubaiFlorida does not lend, arrange loans, or refer visitors to lenders. Only a licensed lender can review credit or approve a loan.
Next step
Begin with a planning brief.
Three short steps turn your direction, timing, and questions into a brief you can review and print. In this preview, nothing is sent or stored.